
Payment Systems Regulator consults on making Confirmation of Payee rules permanent and widening their reach
The Payment Systems Regulator (PSR) has opened a consultation on the future of Specific Direction 17 (SD17), the rule that underpins Confirmation of Payee (CoP) checks across Faster Payments and CHAPS.
The regulator is proposing to remove the direction’s fixed expiry date of 1 November 2026, so that it continues to apply indefinitely, and is also seeking views on whether its scope should be broadened to cover all payment service providers (PSPs) that offer CoP, including those doing so voluntarily.
What Confirmation of Payee does
CoP was introduced to prevent misdirected payments by checking whether the name on a payee’s account matches the name and account details supplied by the person making the payment.
It was also expected to help cut down on authorised push payment (APP) fraud. According to research cited by the PSR, transactions where the name of the expected recipient does not match the account are 25 times more likely to be fraudulent.
SD17 required the PSPs it covered to run a system capable of both sending and responding to CoP requests. Since the direction came into force, uptake has been strong:
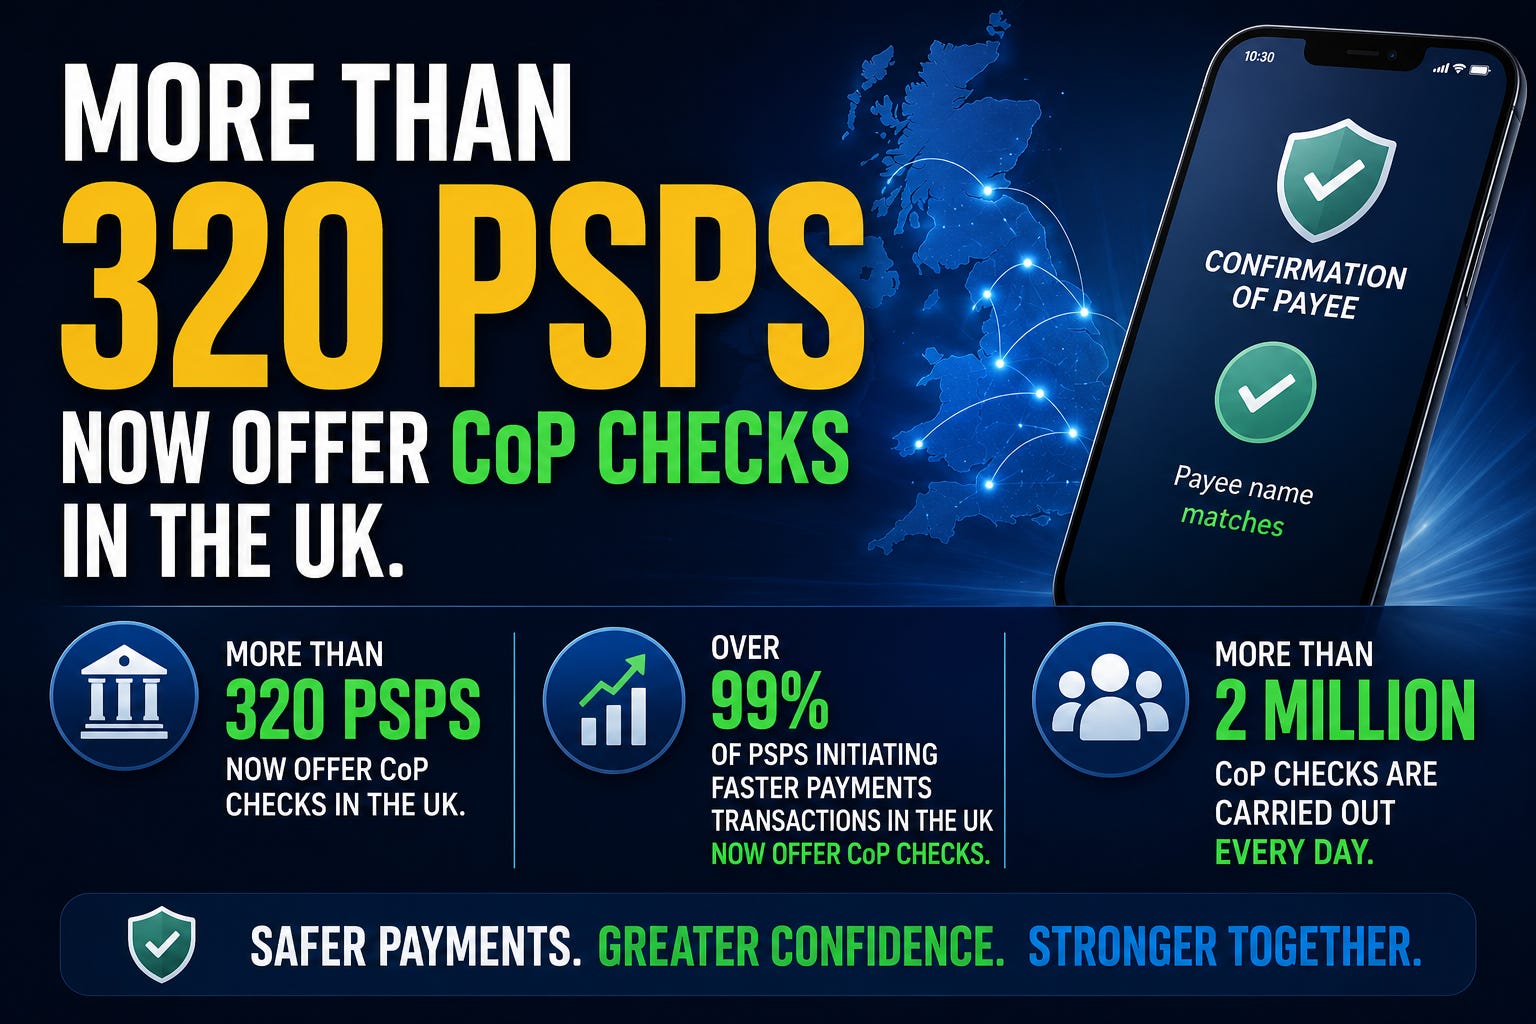
The effect on misdirected payments has also been significant. Pay.UK data shows that, since CoP launched, Faster Payments has seen a 59% reduction in claims for payments sent to the wrong account, alongside a 20–40% reduction in losses to end users for certain types of fraud.
Why the PSR wants to remove the expiry date
The PSR argues that CoP continues to serve its original purpose of tackling misdirected payments and specific forms of APP fraud, and that maintaining broad coverage across the industry is central to that goal.
As things stand, SD17 is due to expire on 1 November 2026, after which there would be no regulatory requirement for PSPs to offer CoP. The regulator is concerned that, despite near-universal adoption, participation could decline once the obligation lifts — particularly because any PSP entering the market after that date would face no requirement to provide the service, leaving firms on an uneven footing.
Because CoP functions as a network service that depends on both sending and receiving PSPs taking part, the PSR believes it is appropriate to keep the regulatory framework in place.
A broader strategic goal
The PSR frames the proposals as part of its wider strategic priority of ensuring people are adequately protected when using UK payment systems. It suggests that sustaining confidence in account-to-account payments also supports other initiatives aimed at giving consumers more choice in how they pay, including the ongoing development of open banking.
Should the expiry date be removed, the PSR says it will continue to monitor how effective and proportionate the direction remains, and will consider further changes if needed.
It is also asking for views on whether SD17 should be reviewed after a set period — five years, for example — or triggered by a particular event.
How to respond
The PSR is inviting comments on its proposals, with a deadline for responses of 20 August 2026.